Fluidstack Hits $18B Valuation on AI Data Center Boom
Fluidstack, an Oxford-founded neocloud backed by Google, has reached a roughly $18 billion valuation on the back of a ~$50B Anthropic deal and Google TPU hosting.
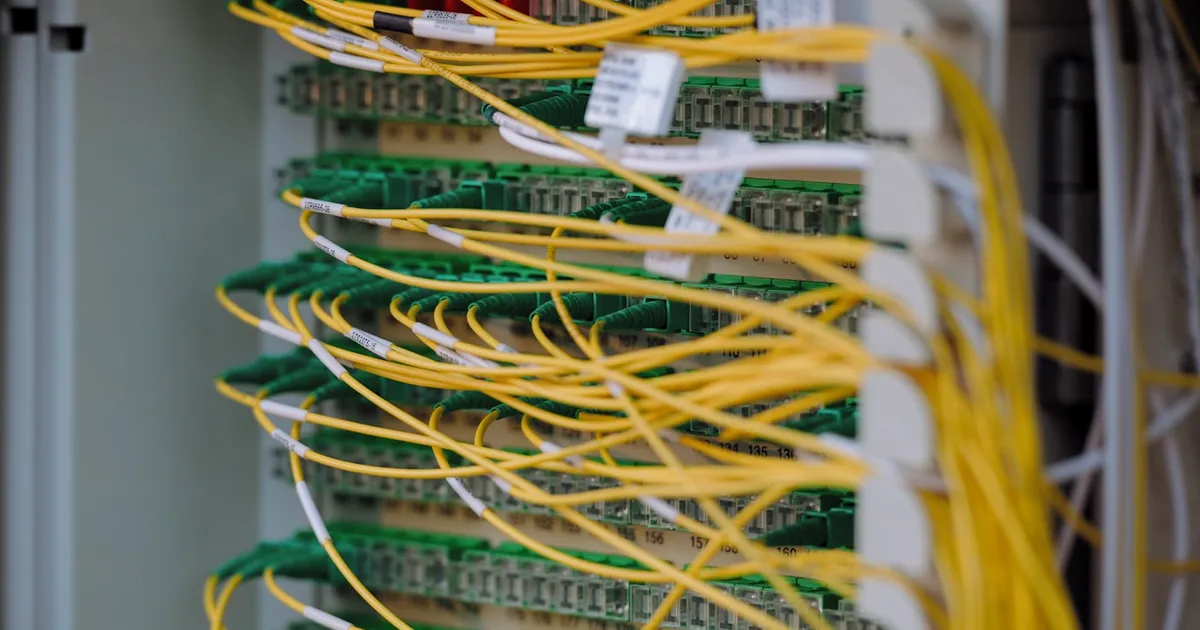
A year ago almost no one outside the AI-infrastructure world had heard of Fluidstack. Now investors are valuing the Oxford-founded company at roughly $18 billion. According to reporting around September 3, 2026, Fluidstack has reached that mark as it raises fresh capital, with reports putting the round in the region of $1 billion to $1.5 billion and naming quantitative trading firm Jane Street among the investors chasing it. The step-up is dramatic: the company was valued at about $7.5 billion as recently as December 2025, meaning its worth has more than doubled in roughly nine months.
The final size and terms had not been formally confirmed by Fluidstack as of reporting, so the numbers carry the usual caveats of a round that is still coming together. But the direction is unambiguous, and the reason is specific: Fluidstack has attached itself to two of the most consequential relationships in the current AI buildout — a giant compute commitment from Anthropic and a role hosting Google’s custom AI chips.
What Fluidstack actually is
Fluidstack is a “neocloud” — a specialized provider that develops and operates data centers and rents out AI compute capacity to labs and enterprises, rather than a hyperscaler running a general-purpose cloud. The category has become one of the defining business models of 2026, riding the hyperscaler capex surge as demand for training and inference capacity outstrips what the big clouds can build alone.
What distinguishes Fluidstack from a traditional data center operator is how asset-light its model is. The company’s value comes less from owning silicon outright than from orchestrating capacity — securing power, sites, and construction, and lining up the chips and tenants that make a facility bankable. That structure lets a relatively small company punch far above its headcount, but it also means its valuation rests heavily on the strength of the contracts it can sign rather than on a balance sheet of hard assets.
Those contracts have grown quickly. Fluidstack’s reported revenue climbed from under $2 million in 2022 to tens of millions by 2024, with some accounts projecting a further leap into the mid-hundreds of millions this year as its anchor deals ramp. It is the same flywheel visible across the category, where peers like Crusoe, Nebius, and SoftBank’s SB Neo have each spun anchor contracts into rapidly rising valuations.
The Anthropic anchor
The single largest driver of Fluidstack’s momentum is a long-term partnership with Anthropic valued at roughly $50 billion. Under the arrangement, Fluidstack is building dedicated data centers in Texas and New York to give the Claude maker greater control over its own computing capacity as demand for its models accelerates.
For Anthropic, the deal is one piece of an infrastructure strategy that has the company committing to compute across multiple partners and geographies, including its previously reported $35 billion Texas data center effort with Lambda. For Fluidstack, a $50 billion anchor is transformational: a commitment of that scale is exactly the kind of contracted, multi-year revenue that lenders and equity investors want to see before underwriting the enormous cost of building AI-grade facilities. In the neocloud model, each anchor tenant unlocks more financing, which funds more capacity, which attracts the next tenant — and a customer the size of Anthropic resets what the company can raise.
The Google TPU connection
The second pillar is Fluidstack’s role with Google. The company hosts Google’s Tensor Processing Units — the search giant’s custom AI accelerators — in third-party data centers, part of a strategic push by Google to distribute its TPU capacity beyond its own facilities. That distribution matters because it is how Google is trying to turn an internally used chip into a broader competitive alternative to Nvidia’s GPUs.
The Anthropic and Google threads are intertwined. Google has confirmed that Anthropic is the only publicly named customer running TPUs in Google’s own data centers, and Fluidstack sits in the middle of the expansion of that footprint into external sites. Being the operator that helps Google extend its silicon into third-party halls — while simultaneously building for Anthropic — places Fluidstack at the intersection of two of the buildout’s biggest bets, and explains why investors are willing to underwrite an $18 billion price on a company that was obscure a year ago.
Why the valuation is what it is
Fluidstack’s markup is not happening in isolation. It is the latest data point in a wave of neocloud financings that share a common structure: sign long-term contracts with a small number of very large customers, then use those contracts to raise the debt and equity needed to buy or secure chips and build facilities. The model can compound fast when demand is booming, and 2026 has been nothing but booming.
That same structure is what makes the category worth watching carefully. A valuation underwritten by a handful of anchor contracts assumes those contracts hold and that AI compute demand keeps climbing for years. Both look plausible today. Both are also the kind of assumption that looks very different if AI spending cools or if a major customer renegotiates. The economics are unforgiving in the other direction too: as we’ve written on AI data center economics, the binding constraint on the entire buildout is increasingly not chips but power — the electricity and grid interconnections needed to bring facilities online, on timelines that can stretch years.
Concentration cuts both ways
Fluidstack’s customer list is its greatest strength and its clearest risk in the same breath. Anchoring the business on Anthropic and Google gives it credibility, scale, and contracted revenue few competitors can match. It also means an outsized share of the company’s future depends on a very small number of counterparties whose own plans are subject to change — and on an asset-light model that leans on partners for the silicon at the center of the whole enterprise.
There is a strategic dependency layered on top. Fluidstack’s Google relationship ties part of its fortunes to how successfully Google can push TPUs as a credible alternative to Nvidia. If that effort gains traction, Fluidstack is positioned as a key distribution partner; if it stalls, one of its two pillars weakens. The company is, in effect, a leveraged bet on both Anthropic’s compute appetite and Google’s silicon ambitions holding up together.
What it means
Fluidstack’s climb to a roughly $18 billion valuation is a clean read on where private capital thinks AI infrastructure is headed: up, fast, and increasingly through specialized intermediaries rather than the hyperscalers alone. A company that was worth $7.5 billion at the end of last year has more than doubled by attaching itself to a $50 billion Anthropic commitment and a role in Google’s TPU expansion — proof that in this cycle, the right anchor contracts can be spun into eye-watering valuations almost overnight.
The immediate winners are clear. Fluidstack gets the capital to keep building; its backers, reportedly including Jane Street, get exposure to two of the buildout’s marquee names through a single vehicle; and Google gains a partner to widen its chips’ reach. The chip and power suppliers feeding these facilities win too, as every new hall means more orders.
The risks are the mirror image of the strengths. Valuations built on a few very large contracts assume those contracts hold and that AI demand keeps climbing. An asset-light neocloud is only as durable as its partners’ commitments and its access to power. What to watch next: whether Fluidstack formally confirms the round and its terms; whether the neocloud markups keep climbing or start to plateau as more capacity comes online; and, above all, whether the anchor customers powering these valuations keep spending at the pace the whole structure assumes. For now, the market’s answer is a resounding yes — priced, in Fluidstack’s case, at eighteen billion dollars.
Tagged
Keep reading
 Kurumi · · 5 min read
Crusoe Hits $30B Valuation in $3B AI Data Center Raise
AI data center builder Crusoe raised over $3 billion at a $30 billion valuation, roughly tripling its worth in ten months as Mubadala and others piled in.
Kurumi · · 5 min read Vantage Data Centers Eyes $100B IPO or Sale
Vantage Data Centers is weighing an IPO at about a $100 billion valuation or an outright sale, in what would be the largest data center listing to date.
 Chisato · · 5 min read
Nvidia Australia AI Factories: 2 GW Buildout by 2027
Nvidia lined up eight Australian data center operators to build up to 2 GW of AI factory capacity by 2027, roughly doubling the nation's compute footprint.